TL;DR: When a PIP carrier denies a claim without a reasonable basis, delays payment to pressure a claimant, or ignores clear medical evidence, that conduct may cross into bad faith under Florida law. Bad faith cases arise not from every denied claim, but from patterns of unreasonable investigation, arbitrary decision-making, and prioritizing profit over contractual duty. Recognizing the line between a legitimate denial and bad faith can unlock remedies beyond the policy limits.
A PIP denial letter arrives. The bills are real. The treatment was necessary. The policy was paid for and in force. Yet the carrier says no, offering a sentence or two of explanation, a reference to a peer review, or silence on key evidence. Everything feels uncertain. The medical providers are calling. Work has been missed. The injury is not in question, but the payment is nowhere in sight. What separates a wrongful denial from one that supports a bad faith case is not always obvious, but it is never arbitrary. The distinction lies in how the carrier treated the claim, what it ignored, and whether it placed its own interests above the duty it owed when the premium was accepted. You do not have to sort through that alone.
Personal Injury Protection coverage in Florida operates under a no-fault framework designed to provide medical and wage-loss reimbursement regardless of who caused the accident. Florida Statutes § 627.736 requires insurers to pay 80 percent of reasonable medical expenses (capped at $10,000 for a diagnosed emergency medical condition or $2,500 otherwise) and 60 percent of lost wages, up to the policy limit. While the statute mandates payment within 30 days of receiving written notice of a covered loss, the legal standard for penalizing insurers has tightened. When a carrier denies a claim, it must still do so on a legally and factually sound basis; however, mere negligence or a cursory investigation is no longer sufficient to prove bad faith. Bad faith now requires demonstrating a higher level of wrongful intent or reckless disregard, and insurers are shielded entirely from bad faith claims if they pay within a 90-day safe harbor period. Furthermore, the law now imposes a reciprocal duty of good faith on the claimant when making demands and providing information.
What Constitutes Bad Faith in PIP Denial Cases
Bad faith under Florida law is not mere negligence. It is the failure to act fairly and honestly toward the insured, with due regard for the insured’s interests, in practical terms, denying a claim without a reasonable basis, while knowing the basis was absent or recklessly disregarding whether it existed. Florida Statutes § 624.155 creates a statutory civil remedy against an insurer that fails to settle a claim in good faith or otherwise engages in the unfair claim settlement practices described in Florida Statutes § 626.9541. Pursuing that statutory remedy requires filing a Civil Remedy Notice with the Department of Financial Services and giving the insurer 60 days to cure. An insurer may act in bad faith when it prioritizes cost containment over claim validity, ignores favorable evidence, relies on biased or incomplete expert opinions, or applies policy language in ways no reasonable insurer would.
The claim file often tells the story. Adjusters who never request key medical records, who rely solely on a desk review without considering diagnostic imaging, who ignore treating physician opinions in favor of a single medical examiner hired by the carrier, or whodeny a claim before the investigation is complete; these patterns suggest the decision was made for reasons other than the facts. Bad faith is rarely about a single misstep. It is about a posture: the carrier decided the outcome before it examined the claim.
Common Triggers That Elevate a Denial Into Bad Faith Territory
Certain fact patterns recur in bad faith litigation. Not every denied claim rises to that level, but specific conduct by the insurer consistently draws scrutiny. Understanding these triggers helps distinguish legitimate coverage disputes from improper claim handling.
- Reliance on a biased compulsory medical examination: When the carrier sends nearly every claimant to the same examining physician, and that physician’s opinion contradicts both the treating doctor and objective diagnostic findings, the denial may lack a reasonable basis.
- Failure to investigate: Denying a claim without requesting medical records, without reviewing MRI or X-ray results, or without contacting the claimant can demonstrate indifference to the truth of the claim.
- Ignoring clear medical causation: When the accident, the onset of symptoms, and the treatment all align, and the carrier denies the claim based on speculation about pre-existing conditions without supporting evidence, that decision may be indefensible.
- Unreasonable delay followed by denial: Waiting until the claimant is financially desperate, then offering a fraction of what is owed or denying the claim outright, can indicate tactical bad faith designed to leverage hardship into settlement.
- Misrepresentation of policy terms: Citing exclusions that do not apply, misstating the scope of coverage, or interpreting ambiguous terms against the insured without legal justification can support a bad faith claim, particularly when the carrier’s own records contradict the denial.
- Blanket denials without individualized review: Applying a one-size-fits-all rationale, such as categorically cutting off care beyond acertain visit count regardless of injury severity, ignores the statute’s requirement that expenses be reasonable, related, and medically necessary on a case-by-case basis.
These patterns do not prove bad faith in isolation. But once a claimant presents evidence that the denial was unreasonable, the carrier’s process comes under the microscope, and it must be able to show that process was sound.If it cannot, the denial may not only be reversed. It may open the door to damages beyond the policy limit.
The Role of the Claim File and Internal Communications
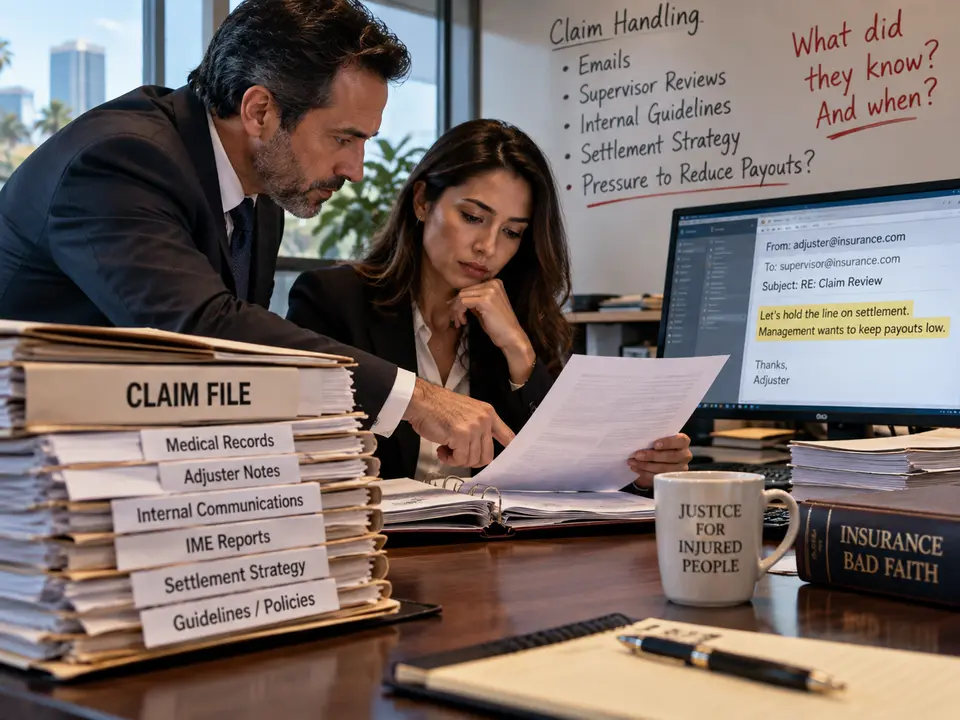
Discovery in a bad faith case centers on the insurer’s claim file. Emails between adjusters and supervisors, internal guidelines on claim handling, the selection process for examining physicians, notes on settlement strategy, and any documentation of pressure to reduce payouts can all become evidence. Carriers that operate in good faith maintain thorough, contemporaneous records that justify each decision. Carriers that do not often reveal as much in their own notes.
The claim file also shows what the adjuster knew and when. If the file contains medical records clearly supporting the claim, yet the denial letter references only the examiner’s report, that discrepancy can be powerful evidence. If the adjuster’s notes show awareness that the denial was questionable but the carrier proceeded anyway under internal pressure, that can establish knowledge or reckless disregard. The file is the insurer’s own record of how it treated the claim, and in bad faith cases, it often becomes the most damaging exhibit.
Damages and Remedies Available in a PIP Bad Faith Case
A successful bad faith claim in Florida can yield several categories of damages. First, the claimant is entitled to the benefits wrongfully withheld, the principal amounts owed under the PIP policy. Second, statutory interest accrues on overdue benefits from the date payment was due. Third, the claimant may recover attorney’s fees and costs under Florida’s insurance fee-shifting provisions, which are designed to encourage insurers to pay valid claims promptly.
Beyond those contract-based remedies, a bad faith claim can open the door to compensatory damages for consequential harm: the financial distress caused by the wrongful denial, damage to credit, emotional distress, and other harm that flowed directly from the insurer’s misconduct. Where the conduct is particularly egregious, punitive damagesmay be available, but Florida law sets a high bar; § 624.155 permits punitive damages only where the insurer’s acts occurred with such frequency as to indicate a general business practice and were willful, wanton, malicious, or in reckless disregard of the insured’s rights. Punitive damages are not capped by the policy limit. For a claimant with a $10,000 PIP policy, a bad faith outcome can exceed the face value of the coverage many times over, transforming a denied claim into a Tampa car accident claim with significant stakes for both parties. Every case is different, and outcomes depend on the specific facts and evidence.
How Insurers Defend Against Bad Faith Allegations
Insurance carriers facing bad faith claims typically assert that the denial was based on a reasonable interpretation of policy language, a legitimate coverage defense, or credible medical opinion. They may argue that the claimant’s treatment was not medically necessary, that the injury was pre-existing, or that the provider’s charges were unreasonable. These defenses are not inherently improper. The question is whether the insurer conducted a fair investigation and applied the policy terms in good faith.
A carrier that requested all relevant records, consulted qualified medical experts, applied consistent standards across claims, and articulated a clear, fact-based rationale for denial can often defeat a bad faith claim even if the denial is later reversed. The law does not require insurers to be correct, it requires them to be reasonable. The problem arises when the insurer’s process is a sham: when the outcome was predetermined, the expert was selected for a predictable opinion, or the adjuster set aside evidence that contradicted the desired result. At that point, the defense weakens, and the claim file itself becomes the claimant’s strongest proof.
Carriers also defend by pointing to coverage disputes that involve genuine questions of law or fact. If a medical bill is coded incorrectly, if treatment fell outside the statutory requirements, or if the provider is not licensed as the statute requires, the denial may be defensible even if the claimant ultimately prevails. Bad faith requires more than a wrong decision, it requires a decision made without a reasonable basis or with knowledge that the basis was insufficient. Where ambiguity exists and the insurer’s interpretation is plausible, bad faith is difficult to prove. But where the facts are clear, the treatment is documented, and the policy is unambiguous, a denial unsupported by the record is more than wrong. It may expose the carrier to liability well beyond the original claim. Understanding that distinction is essential when evaluating whether a PIP denial warrants escalation to a bad faith case.
The line between a wrongful denial and a bad faith denial is drawn by the insurer’s conduct, not by the claimant’s injury. A carrier that investigates thoroughly, applies policy terms fairly, and pays valid claims promptly fulfills its duty. One that cuts corners, ignores evidence, or uses delay as leverage does not. The consequences reach beyond the individual claim. They signal whether an insurer honors the bargain struck when the premium was paid or whether it treats every claim as an opportunity to avoid an obligation. When the latter is true, Florida law provides a remedy, and it is not always confined to the policy limit.
Closing Remarks
If a PIP carrier has denied a claim without requesting key medical records, if the denial relies solely on a carrier-selected examiner while ignoring the treating physician, or if the insurer delayed payment for months only to offer a fraction of what was owed, the conduct may be more than a coverage dispute. You do not have to face this alone. CDB Injury Law represents Florida claimants whose valid claims have been wrongfully denied and who are carrying the financial and emotional weight of an insurer’s broken promise. Let us talk about your recovery, your claim, and the remedies available when an insurance carrier places profit over obligation.
Frequently Asked Questions
What is the difference between a denied PIP claim and a bad faith case?
A denied PIP claim is simply a coverage decision, an insurer’s determination that benefits are not owed under the policy terms. A bad faith case arises when that denial lacks a reasonable basis, when the insurer ignored clear evidence supporting the claim, or when the carrier prioritized cost savings over its contractual duty. Not every denied claim is bad faith, but every bad faith case begins with a denial that should not have occurred.
Can a PIP carrier deny a claim based solely on a medical examination it arranged?
An insurer may consider the opinion of a physician it retains, but it should not disregard all other evidence in favor of that opinion alone, especially when it conflicts with treating physicians, diagnostic imaging, and contemporaneous medical records. If that report is the only basis for denial and the rest of the evidence supports the claim, the denial may be unreasonable. The carrier is expected to weigh the full record rather than select the single opinion that justifies non-payment.
What damages are available in a Florida PIP bad faith case?
Damages can include the wrongfully withheld benefits, statutory interest, attorney’s fees and costs, and compensatory damages for financial and emotional harm caused by the denial. Punitive damages are possible but limited: under Florida Statutes § 624.155, they generally require proof that the insurer’s conduct was willful, wanton, malicious, or in reckless disregard of the insured’s rights and occurred with such frequency as to indicate a general business practice. Results depend entirely on the facts of each case.
How long does it take to prove bad faith in a PIP case?
The timeline varies based on the complexity of the claim, the carrier’s willingness to produce the claim file, and whether the case proceeds to trial or settles. Discovery often reveals the insurer’s internal decision-making process within months, but litigating a bad faith case to verdict can take a year or more. Bad faith claims are not resolved through the same streamlined procedures as routine PIP benefit disputes, they involve broader discovery and remedies, which can extend the timeline.
Can a claimant pursue a bad faith claim without first resolving the PIP dispute?
Generally, no. Under Florida law, a first-party bad faith claim does not accrue until the underlying coverage and damages questions are determined in the insured’s favor. A claimant must also file a Civil Remedy Notice with the Department of Financial Services under Florida Statutes § 624.155 and give the insurer 60 days to cure the violation. Once that foundation is in place, the bad faith claim can move forward as a separate action, though it still depends on proving that the denial was both wrong and unreasonable.
References
- Florida Statutes § 627.736 (Florida Motor Vehicle No-Fault Law, required personal injury protection benefits).
- Florida Statutes § 624.155 (Civil remedy for insurer bad faith, including Civil Remedy Notice requirement).
- Florida Statutes § 626.9541 (Unfair methods of competition and unfair or deceptive acts, including unfair claim settlement practices).